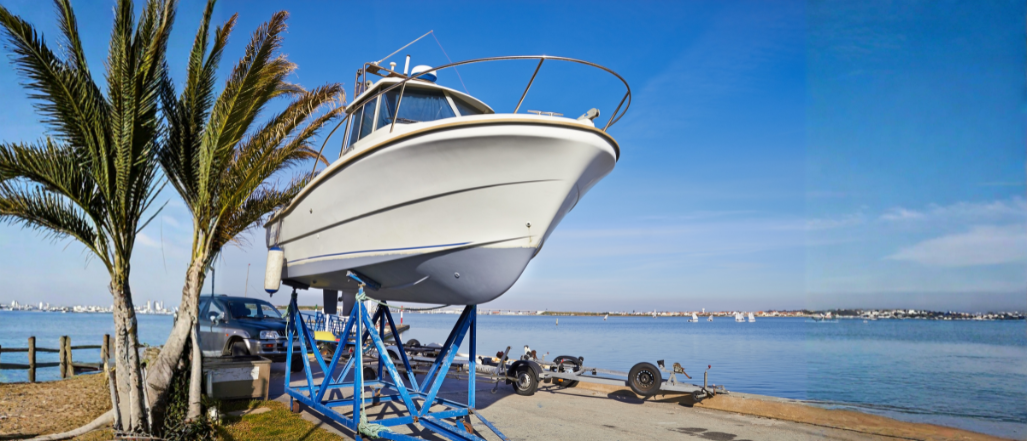
Boat repair and servicing businesses have multiple risk factors to consider, both on and off the water.
In addition to the business’s physical location and equipment, owners must consider the protection of their clients’ property while it is in their care. Insurance protection needs to cover a number of bases, including the business, its employees, customers, and other third parties (such as vendors and contractors) who might be on the property or working on the water.
With people in and out of the area, accidental damage, third-party injuries, and questions about work performed can all give rise to potential claims.
How does a boat servicing operation protect itself against these risks?
What is marine liability insurance?
Marine liability insurance is coverage designed to protect businesses that need this type of specialized policy. Marinas, boat manufacturing companies, charter vessel operators, and repair and maintenance businesses all need to consider the risks specific to their businesses.
For example, the likelihood of injuries from slips exists at most businesses if the conditions are right, such as slippery floors at entrances when it is raining or snowing out. However, for businesses located on a waterfront, the risk increases significantly because water is ever-present.
Similarly, just as a car repair shop needs to consider the possibility of accidental damage to the cars they are working on, a boat servicing operation needs to consider the potential for damage to the boats in line for repair or maintenance.
Marine liability coverage protects a boat servicing operation from losses associated with accidental property damage, injuries, or issues arising from work performed. It is important insurance for small to midsize boat servicing operations to carry.
What does marine liability insurance cover?
Marine liability insurance primarily covers accidental injuries and property damage that occur in marinas and similar waterfront locations.
For example, if a customer slips on the dock and breaks a wrist and the business is determined to be at fault (such as the cause being a trip on equipment that was left out, or a spill that wasn’t cleaned up), marine liability insurance will cover the medical expenses that arise from the accident.
Policies can be highly specialized and tailored, with additional coverage that is specific to the business.
Most offer coverage such as legal liability protection for ship and watercraft repair work, protecting your business from claims of poor workmanship.
Ship repairers’ legal liability is sometimes included; this protects a repair business if a customer’s boat is damaged while work is being performed, or even during “sea tests” to confirm repairs were successful and holding.
If this coverage is not included in your marine general liability policy, it would be an important addition to consider purchasing separately.
What other types of insurance do boat servicing operations need?
There are a number of insurance products to protect those in maritime businesses, and the types of policies you need may vary.
For instance, marinas located on ocean coasts will experience different conditions than those located on lakes or rivers inland. Smaller repair and maintenance shops that deal with individual private boat owners will have different insurance needs than one that services ferries or tour vessels that operate as part of a business.
With that in mind, here are some additional types of policies you may wish to consider:
- Marine property and casualty insurance – This coverage protects your business from losses associated with non-maritime risks. Theft, business interruption, vandalism, and more are all concerns that are not exclusive to marina operations, but pairing this policy with your marine general liability coverage will provide more comprehensive protection for your business.
- Excess liability and Bumbershoot coverage – For some boat servicing operations, the limits in a standard marine general liability policy may not offer enough coverage. Bumbershoot policies are umbrella policies for the maritime industry (“bumbershoot” is an American slang word for umbrella that originated in the late 1800s) that offer protection from losses that exceed standard policy limits.
- Accidental Pollution – Sometimes this is included in general marine liability policies, but increasingly it is sold as a separate policy. That’s because pollution risks can be very expensive to remediate, and depending on the size and location of the spill and damage caused, there could be reputational risks and regulatory fines.
- Workers Compensation – Virtually every state requires employees be covered by a workers compensation policy, so if you have one or more employees, you will likely need this insurance coverage.
How much does marine liability insurance cost?
Insurance policies are based on risk, and that can vary significantly based on things like where your boat servicing business is located, the types of boats the company works on, the business size and number of employees, and annual revenue.
With so much potential variation, if you want to know more about marine liability insurance, it makes sense to call the experts at Rate Insurance. With access to a wide range of commercial insurers, they can help you find the right marine liability insurance policy to meet the needs of your boat servicing business.
Disclaimer:
All information provided in this publication is for informational and educational purposes only, and in no way is any of the content contained herein to be construed as financial, investment, or legal advice or instruction. Rate Insurance does not guarantee the quality, accuracy, completeness or timelines of the information in this publication. While efforts are made to verify the information provided, the information should not be assumed to be error free. Some information in the publication may have been provided by third parties and has not necessarily been verified by Rate Insurance. Rate Insurance, its affiliates and subsidiaries do not assume any liability for the information contained herein, be it direct, indirect, consequential, special, or exemplary, or other damages whatsoever and howsoever caused, arising out of or in connection with the use of this publication or in reliance on the information, including any personal or pecuniary loss, whether the action is in contract, tort (including negligence) or other tortious action.